Property Protection for Expats in Germany
Home Insurance in Germany: Why Natural Hazard Cover Matters
Home insurance in Germany for expats starts with one question: is your building covered against flooding and heavy rain? Standard building insurance typically covers fire, storm, hail and tap water damage, but natural hazards only when you add them.
If you own a house or an apartment building in Germany, building insurance (Wohngebäudeversicherung) protects the structure itself: walls, roof, heating, pipes and fixed installations. For most owners, the property is the most expensive purchase of their life.
Many policies are sold on price. Comparison portals make it easy to save a little each year. But the cheapest tariff is often cheap because something is missing, and the most common gap is natural hazard cover (Elementarschäden).
Do not save €100 a year on your building insurance if the price is a policy that does not pay when water stands in your cellar. The saving is small. The potential loss is far larger.
What Standard Building Insurance Covers and What It Does Not
A basic building insurance policy in Germany typically covers damage from fire, lightning, explosion, storm and hail, and tap water damage from burst pipes.
Natural hazards such as flooding, heavy rain, backwater from the sewer, earthquake, landslide, snow pressure and avalanche are usually covered only when natural hazard cover (Elementarschadenversicherung) is added to the policy. Without it, the insurer may refuse to pay.
For expats this is easy to miss. Policy documents are in German, terms like Starkregen and Rückstau are rarely explained, and it is easy to assume that the house is simply insured.
Natural Hazard Cover Did Not Become Important in 2021
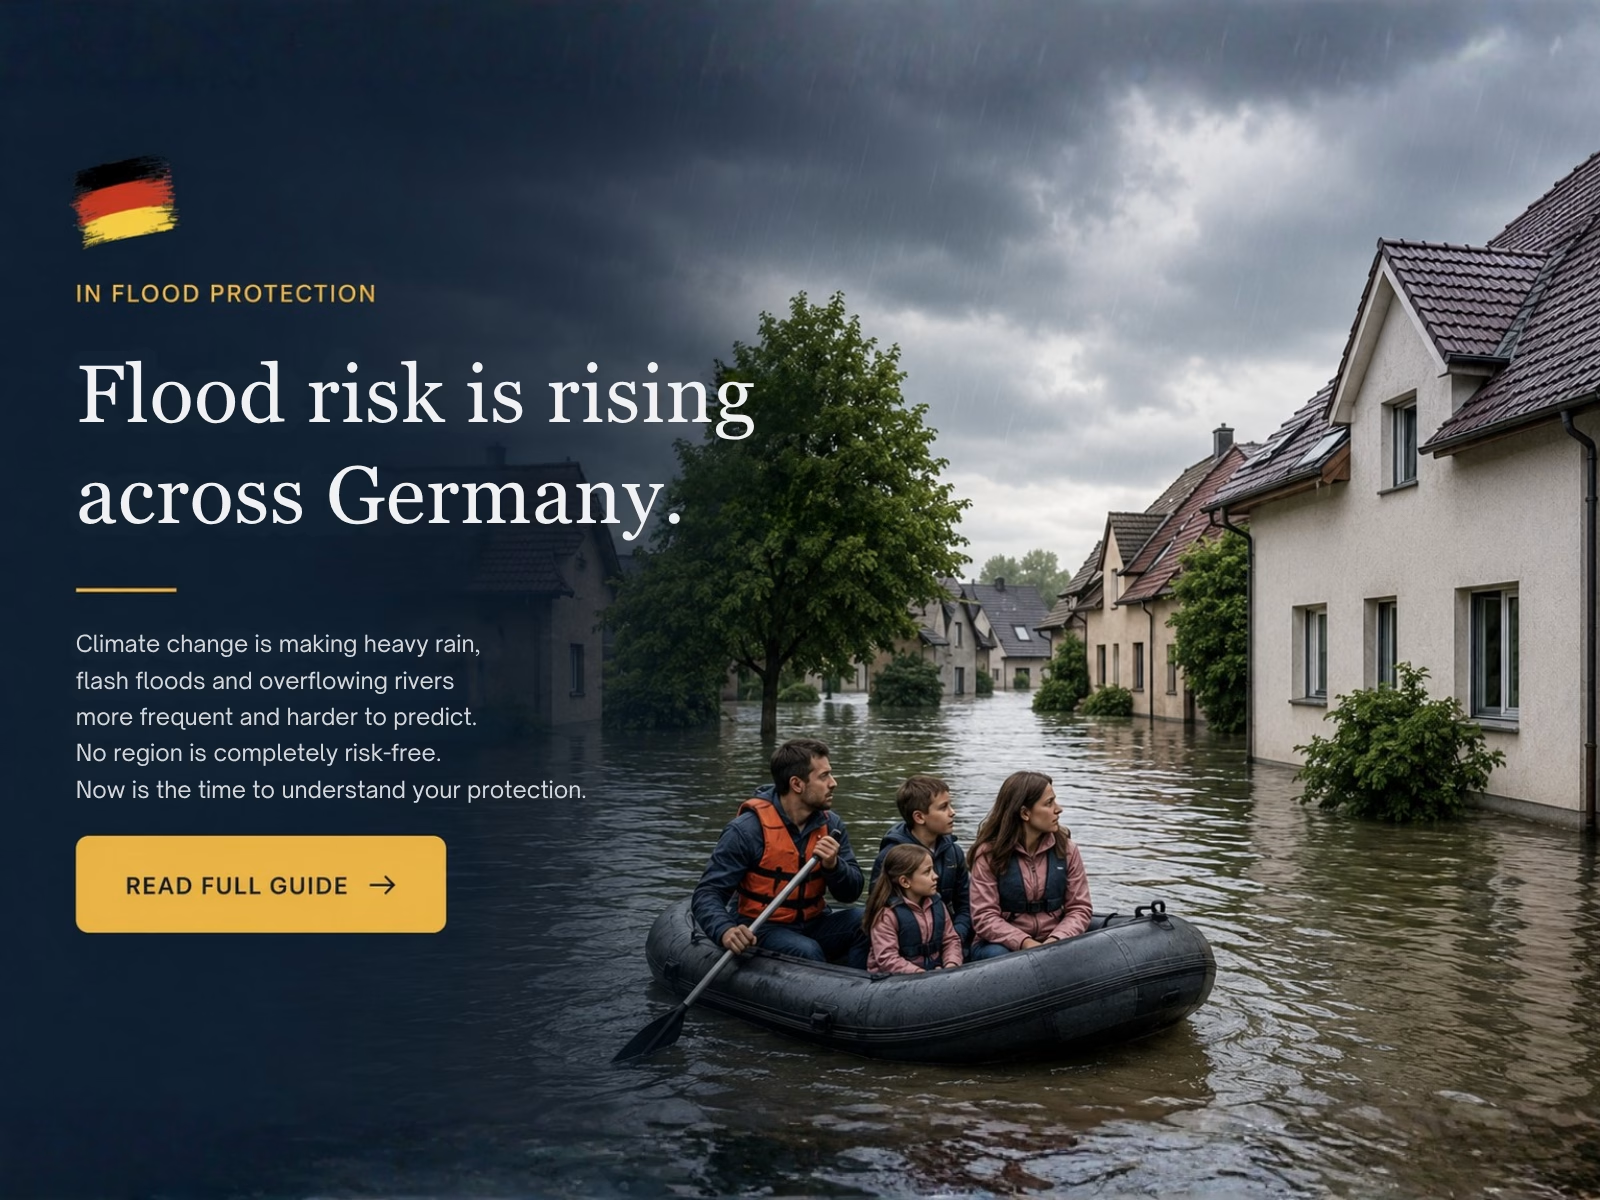
The floods in the Ahr valley and in North Rhine-Westphalia in July 2021 made the risk visible to everyone. But heavy rain, flash floods and overflowing rivers can affect homes in many regions of Germany, not only in known flood zones. A house far from a river can still be hit by heavy rain or backwater.
- Flooding and overflowing rivers
- Heavy rain (Starkregen)
- Backwater from the sewer (Rückstau)
- Earthquake and landslide
- Snow pressure and avalanche
Which of these risks apply to you depends on your location and the policy terms. A good adviser checks the actual risk and the exact wording, not only the premium.
Will Natural Hazard Cover Become Mandatory?
The German federal government has been discussing making natural hazard cover a mandatory module for new building insurance policies. Details and timing may change, so please check the current status before you rely on it.
Whatever happens politically, the practical advice stays the same: do not wait for a rule. If you buy or already own a property, review your cover now.
How to Choose Your Home Insurance in Germany
Look at the sum insured, natural hazard cover with sufficient limits, the treatment of heavy rain and backwater, and any waiting periods or deductibles. Our guide to homeowner insurance in Germany explains the basics.
If you are buying a property, check this before you sign the purchase contract. Lenders often require building insurance as part of the mortgage.
Tenants do not need building insurance because the landlord insures the building. For your own belongings, household insurance in Germany is the relevant policy.
How German Sherpa Approaches Property Protection
At German Sherpa, we do not look for the cheapest tariff. We look at what your building needs: its location, value and risks. We recommend what makes sense for you, not what pays the highest commission.
We compare reliable providers and check that natural hazard cover is part of the policy, so that you are not left alone with the loss when it matters.
If you want to know whether your building is properly covered, book a free Financial Clarity Call and we will review your current policy with you.
Protect Your Biggest Investment Before You Need To
If you own property in Germany, review your building insurance now, especially your natural hazard cover. A short check today can prevent a very expensive surprise later.
This article is for general information only. Insurance terms, exclusions and benefits vary by provider and tariff. It is not individual advice.
Clarity Starts With Structure.
We advise expats who live and work in Germany.
Free Financial Clarity Call
Not sure what applies to you?
Book a free 30-minute call. We look at your situation, answer your first questions and show you what to look at first, in English and without sales pressure.
Book your free Clarity Call →Free · 30 minutes · Online
 Marcel PlumFounder, German Sherpa